How Commercial Property Can Help Build Long-Term WealthCommercial real estate has long been considered one of the most effective ways to build long-term wealth. Whether it's an office building,

Dated: April 21 2026
Views: 166
Understanding mortgage interest rates starts with knowing that the rate is the cost of borrowing money to buy a home. When you take out a mortgage, the lender charges interest as a percentage of the remaining loan balance. That rate directly affects your monthly payment and the total amount you repay over time. For example, even a change of 0.5% can add or save hundreds of dollars each month depending on the loan size.
Mortgage rates are influenced by several major factors. First is the broader economy: inflation, employment data, and bond market movements often push rates up or down. Mortgage rates tend to follow the yield on the 10-year U.S. Treasury note. Second is Federal Reserve policy. While the Fed does not set mortgage rates directly, its decisions on short-term interest rates influence borrowing costs across the economy. Third is the borrower’s profile. Credit score, debt-to-income ratio, down payment size, loan type, and property use (primary home vs. investment property) all matter.
There are also different mortgage structures. A fixed-rate mortgage keeps the same interest rate for the life of the loan, making payments more predictable. An adjustable-rate mortgage (ARM) usually starts lower, then changes after an introductory period based on market conditions.
In the first quarter of 2026, U.S. mortgage rates stayed mostly in the low-to-mid 6% range for 30-year fixed loans. Freddie Mac reported the average 30-year fixed mortgage at 6.06% in mid-January, 5.98% in late February, then rising to 6.22% by March 19 and 6.38% by March 26. By early April, rates reached 6.46% before easing again. (Yahoo Finance) (Fox Business) (Freddie Mac) (Freddie Mac)
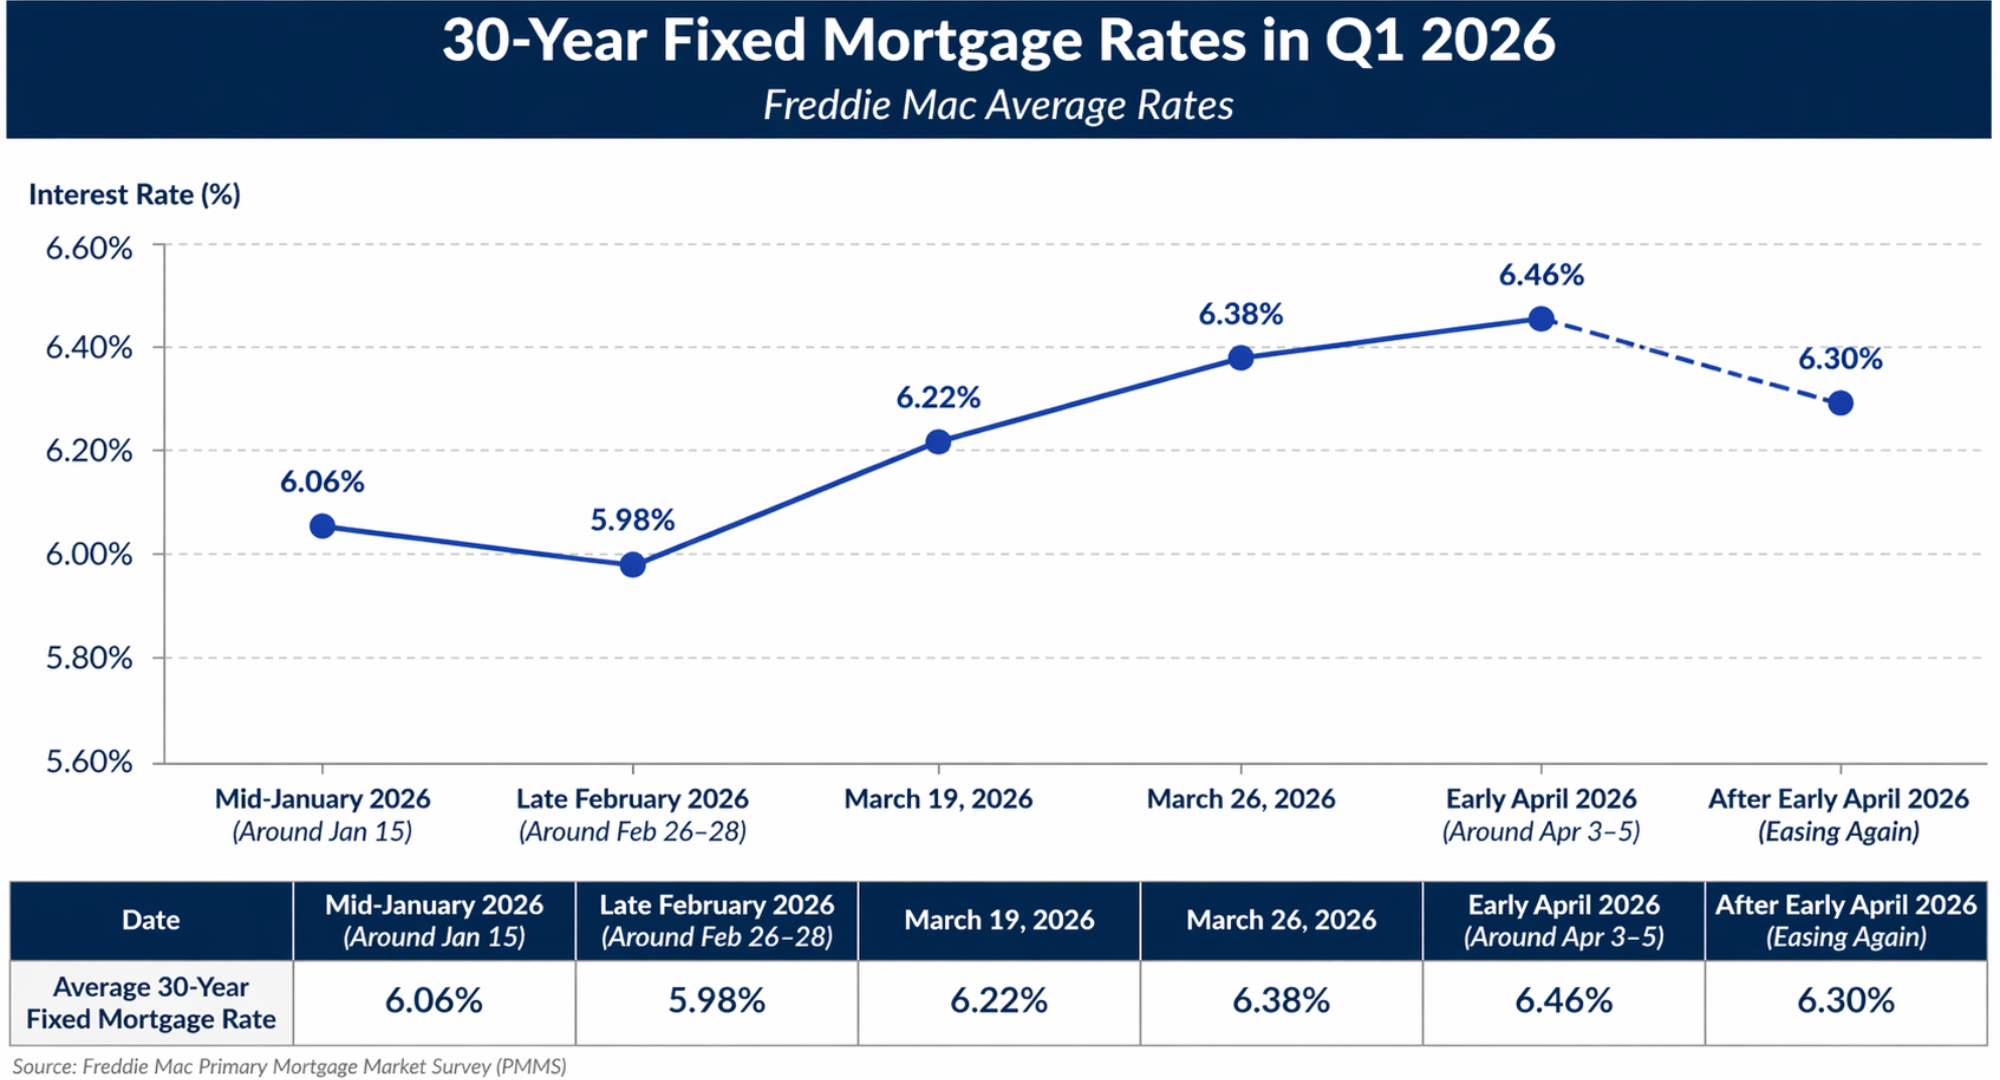
This means Q1 2026 began with improving affordability, but rates climbed toward the end of the quarter. For buyers, understanding this trend is important because timing, lender comparison, and locking a rate can significantly affect long-term costs. Shopping multiple lenders and improving credit before applying remain two of the best ways to secure a better mortgage rate.

Stephen Skots has made it his mission to provide quality real estate service for the past 17 years. He specializes in purchasing and selling both residential and commercial properties. His experience ....
How Commercial Property Can Help Build Long-Term WealthCommercial real estate has long been considered one of the most effective ways to build long-term wealth. Whether it's an office building,
Common Reasons Homes Sit on the Market (And How to Avoid It)Selling a home can be exciting, but if it stays on the market too long, sellers often wonder: Why isn’t my home selling? Here are
Understanding mortgage interest rates starts with knowing that the rate is the cost of borrowing money to buy a home. When you take out a mortgage, the lender charges interest as a percentage of the
Buying a home comes with excitement—and a long list of decisions. One question many buyers face is whether to purchase a home warranty during the transaction.A home warranty is a service
Should you require assistance in navigating our website or searching for real estate, please contact our offices at 916-314-7492.

IDX display powered by Inside Real Estate
 Last updated: September 23, 2026 9:51 AM UTC Property Information © 2026 MLSListings Inc. All rights reserved. Listing information is deemed reliable but not guaranteed. The data relating to real estate for sale on this display comes in part from the Internet Data Exchange program of the MLSListingsTM MLS system. Real estate listings held by brokerage firms other than USKO Realty are marked with the Internet Data Exchange and detailed information about
them includes the names of the listing brokers and listing agents.
The information being provided by CARETS (CLAW, CRISNet MLS, DAMLS, CRMLS, i-Tech MLS, and/or VCRDS)
is for the visitor's personal, non-commercial use and may not be used for any purpose other than to identify
prospective properties visitor may be interested in purchasing.
Any information relating to a property referenced on this web site comes from the Internet Data Exchange (IDX)
program of CARETS. This web site may reference real estate listing(s) held by a brokerage firm other than the
broker and/or agent who owns this web site.
The accuracy of all information, regardless of source, including but not limited to square footages and lot sizes, is
deemed reliable but not guaranteed and should be personally verified through personal inspection by and/or with
the appropriate professionals. The data contained herein is copyrighted by CARETS, CLAW, CRISNet MLS,
DAMLS, CRMLS, i-Tech MLS and/or VCRDS and is protected by all applicable copyright laws. Any dissemination
of this information is in violation of copyright laws and is strictly prohibited.
CARETS, California Real Estate Technology Services, is a consolidated MLS property listing data feed comprised
of CLAW (Combined LA/Westside MLS), CRISNet MLS (Southland Regional AOR), DAMLS (Desert Area MLS),
CRMLS (California Regional MLS), i-Tech MLS (Glendale AOR/Pasadena Foothills AOR) and VCRDS (Ventura
County Regional Data Share)
Show More...
 All measurements and all calculations of area are approximate. Information provided by Seller/Other sources, not verified by Broker. All interested persons should independently verify accuracy of information. Provided properties may or may not be listed by the office/agent presenting the information. Data maintained by MetroList© may not reflect all real estate activity in the market.
All real estate content on this site is subject to the Federal Fair Housing Act of 1968, as amended, which makes it illegal to advertise any preference, limitation or discrimination because of race, color, religion, sex, handicap, family status or national origin or an intention to make any such preference, limitation or discrimination.
MetroList CA data last updated: September 23, 2026 9:20 AM UTC Terms of Use.
Vendor data provided by Inside Real Estate, LLC.
 Bay East ©2026. CCAR ©2026. bridgeMLS ©2026. Information Deemed Reliable But Not Guaranteed. This information is being provided by the Bay East MLS, or CCAR MLS, or bridgeMLS. The listings presented here may or may not be listed by the Broker/Agent operating this website. This information is intended for the personal use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Data last updated at September
23, 2026 9:21 AM UTC
Show More...
 All data, photos, visualizations, and information regarding a property, including the property's compliance with state and local legal requirements and all measurements and calculations of area, have been obtained from various sources, and may include such material that has been generated by use of artificial intelligence. Such information and material have not been and will not be verified for accuracy by the listing broker or the multiple listing service, and are not guaranteed as complete, accurate or reliable. Such information and material should be independently reviewed and verified for accuracy. This information and material are intended for the personal use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Copyright ©2026 Bay Area Real Estate Information Services, Inc. All Rights Reserved.
